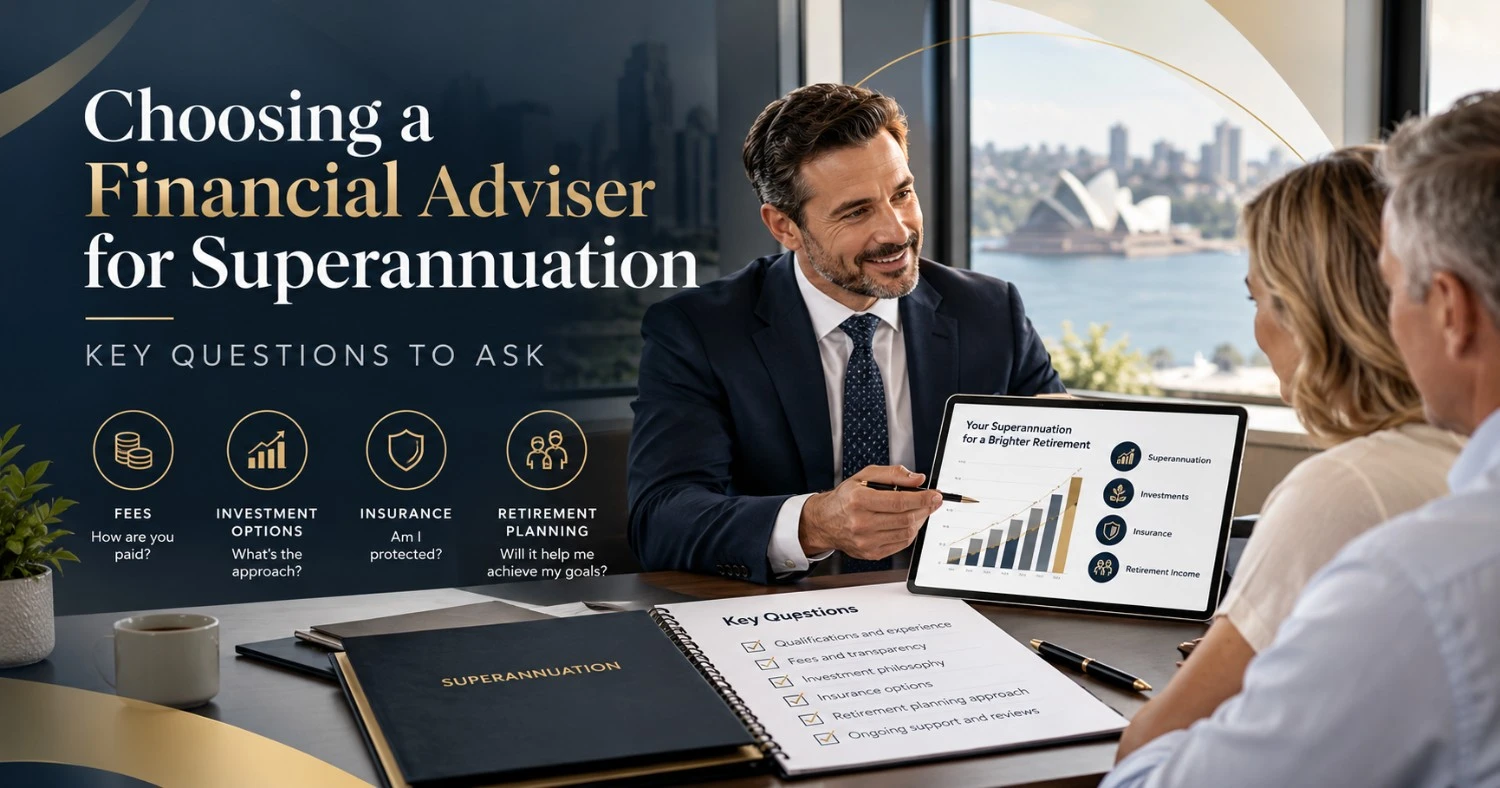
Choosing a Financial Adviser for Superannuation: Key Questions to Ask

• October 26, 2026

Featured Image

Superannuation is one of the most important parts of long-term financial planning, yet many Australians do not review it closely until retirement starts to feel much closer.

Choosing a financial adviser for superannuation can help you understand your options, but it is important to find an adviser whose experience and approach suit your needs.

A good adviser should take the time to understand your goals, explain recommendations clearly and help you understand the risks, costs and trade-offs involved.

Before deciding who to work with, it is worth asking a few key questions.

Why Financial Advice Can Matter for Superannuation

Superannuation decisions can affect more than your account balance.

Depending on your circumstances, your strategy may involve:

  • Contributions
  • Investment options
  • Insurance held through super
  • Retirement income planning
  • Consolidating multiple super accounts
  • Beneficiary nominations
  • Transitioning toward retirement
  • Tax considerations
  • Broader wealth planning

Because these areas can interact, making decisions based only on investment returns or fees may overlook the bigger picture.

This is where professional financial advice can be useful.

1. Are You Licensed to Provide Financial Advice?

One of the first questions to ask is whether the adviser is authorised to provide the type of advice you need.

Financial advice is regulated in Australia, so check that the adviser is appropriately authorised to provide the advice you need and understand which Australian financial services licence or authorisation they operate under.

You can also ask how the adviser’s qualifications and experience relate specifically to superannuation and retirement planning.

This can help you distinguish between general information and personalised financial advice.

2. How Much Experience Do You Have With Superannuation Advice?

Not all financial advisers have the same areas of focus.

Some may specialise in retirement planning, while others work more broadly across investments, wealth creation, insurance or business owners.

Ask how often they advise clients on superannuation matters and what types of clients they typically work with.

For example, your needs may be different if you are:

  • In your 30s and building super
  • Approaching retirement
  • Self-employed
  • A business owner
  • Managing multiple super accounts
  • Considering a self-managed super fund
  • Planning how to draw income in retirement

Relevant experience can help ensure the advice reflects your current circumstances and stage of life.

3. How Will You Understand My Financial Goals?

A good financial adviser should not start with a product.

They should start with you.

Before making recommendations, the adviser should understand your income, assets, debts, superannuation, family situation, risk tolerance and short-term and long-term goals.

Ask what their discovery process looks like.

They should be able to explain how they gather information and how your objectives influence their recommendations.

If the conversation focuses heavily on investment products before your broader circumstances are understood, that may be a sign to ask more questions.

4. How Do You Decide Which Superannuation Strategy Is Suitable?

A recommendation should have a clear reason behind it.

Ask the adviser how they assess whether a particular super strategy suits your circumstances.

They may consider factors such as:

  • Your age
  • Time until retirement
  • Income
  • Contribution levels
  • Investment preferences
  • Risk tolerance
  • Existing super balance
  • Insurance needs
  • Tax position
  • Retirement objectives

A strong adviser should be able to explain not only what they recommend, but why it may be appropriate for you.

5. How Are You Paid?

Understanding fees is essential.

Financial advice may involve initial advice fees, ongoing service fees or other costs depending on the service provided.

Ask for a clear explanation of:

  • Initial advice costs
  • Ongoing advice fees
  • Investment or platform costs
  • Any product-related fees
  • What is included in the service
  • Whether fees are fixed, percentage-based or structured another way

You should be able to understand what you are paying and what you are receiving in return.

Avoid assuming that the lowest-cost adviser is automatically the best option. The quality, scope and usefulness of the advice also matter.

6. Do You Receive Any Benefits From Recommending Certain Products?

It is reasonable to ask how an adviser selects products and whether any commercial arrangements could influence recommendations.

The adviser should be able to explain how products are assessed, what conflicts of interest may exist and how those conflicts are managed.

Transparency is important.

You should feel comfortable asking why a particular super fund, investment option or platform is being recommended over alternatives.

7. What Are the Risks of the Strategy You Are Recommending?

Every financial strategy involves some level of risk.

That risk may relate to investment markets, liquidity, tax outcomes, insurance, contribution rules or retirement timing.

A good adviser should explain potential downsides as clearly as potential benefits.

Ask questions such as:

  • What could go wrong?
  • How might this strategy perform in a market downturn?
  • What happens if my circumstances change?
  • Are there penalties or restrictions I should know about?
  • How flexible is this strategy?

Advice should help you understand the decision, not simply encourage you to accept it.

8. How Will My Investments Be Chosen?

If the advice includes changing your superannuation investments, ask how the investment strategy is constructed.

You may want to understand:

  • Asset allocation
  • Diversification
  • Growth versus defensive assets
  • Risk level
  • Investment timeframe
  • Fees
  • How often the portfolio is reviewed

The appropriate mix will depend on your circumstances.

Someone decades away from retirement may have different priorities from someone planning to retire in the next few years.

9. Will You Review My Insurance Inside Super?

Superannuation often includes insurance, such as life cover or income protection.

Changing funds or consolidating super accounts can sometimes affect existing cover.

Before making changes, ask whether your adviser will review the insurance implications.

This is particularly important if you have existing health conditions, significant financial responsibilities or insurance that may be difficult to replace.

Superannuation decisions should not be considered in isolation from the protection that may already exist within the account.

10. How Often Will My Super Strategy Be Reviewed?

Superannuation planning should not necessarily be a one-time exercise.

Your income, family circumstances, goals and investment environment can all change.

Ask how often your adviser reviews client strategies and what triggers a review.

You should also understand what ongoing advice includes.

For example, will the adviser review:

  • Contributions
  • Investment performance
  • Asset allocation
  • Insurance
  • Retirement projections
  • Legislative changes
  • Your personal circumstances

A clear review process can help keep your strategy aligned with your goals over time.

11. How Will You Explain Your Advice?

Financial advice can become complicated quickly.

A good adviser should be able to explain recommendations in language you understand.

You should feel comfortable asking questions such as:

“Why are you recommending this?”

“What are the alternatives?”

“What happens if I do nothing?”

“What are the costs?”

“What are the risks?”

If you leave a meeting more confused than when you arrived, ask for clarification.

You should understand the strategy before agreeing to it.

Choosing an Adviser Is About More Than Investment Returns

When choosing a financial adviser for superannuation, it can be tempting to focus on who claims to deliver the best investment performance.

But good financial advice involves much more than returns.

It should consider your goals, risk tolerance, tax position, insurance, retirement plans and broader financial circumstances.

The right adviser should help you make informed decisions and understand the reasoning behind them.

W Advisory works with individuals and business owners seeking advice on their finances, superannuation and long-term financial planning..

If you are reviewing your superannuation strategy, [talk to W Advisory about your financial planning needs].

Frequently Asked Questions

What should I look for in a financial adviser for superannuation?

Look for appropriate qualifications and authorisation, relevant experience, transparent fees, a clear advice process and someone who takes time to understand your financial goals before making recommendations.

How much does superannuation financial advice cost?

Costs vary depending on the complexity of your circumstances and the level of service required. Ask the adviser to clearly explain all initial, ongoing and product-related fees before proceeding.

Should a financial adviser review my insurance inside super?

Yes, where relevant. Insurance can be affected by changes to superannuation accounts, so the impact on existing cover should be considered before switching or consolidating funds.

How often should superannuation advice be reviewed?

There is no single schedule that suits everyone. Reviews may be useful when your income, family circumstances, retirement plans or financial goals change, or when your strategy needs to be reassessed.

Is financial advice only useful close to retirement?

No. Advice can also be useful earlier when considering contributions, investment strategy, insurance, account consolidation and long-term retirement planning.
Disclaimer

This information is general in nature and does not constitute personal financial advice. Superannuation, investment, insurance and retirement strategies should be considered in light of your objectives, financial situation and needs. Seek personalised advice from an appropriately qualified and authorised financial adviser before making financial decisions.

Other Blogs

increase small business costs

How Compliance Requirements Can Increase Small Business Costs

Running a small business involves more than delivering products or services and generating revenue. Business owners also need to manage a growing list of compliance obligations, from tax and payroll requirements to workplace rules, record keeping, insurance and industry-specific regulations. Individually, many of these requirements may appear manageable. Together, however, they can create a significant …

tradie accountant NSW

Why You Need a Specialised Tradie Accountant in NSW

Running a trade business involves much more than completing jobs and sending invoices. Between quoting, purchasing materials, managing subcontractors or employees, keeping equipment on the road, following up payments and finding the next job, financial administration can easily get pushed down the priority list. But overlooking the numbers can create problems. Tax obligations, inconsistent cash …

Featured Image
We will help business owners and
professionals overcome the burden of
poor tax advice, and inefficient structures

by delivering tailored strategies
that are compliant, minimise tax
and are structured to create
generational wealth.

Call Us Book Free Consultation